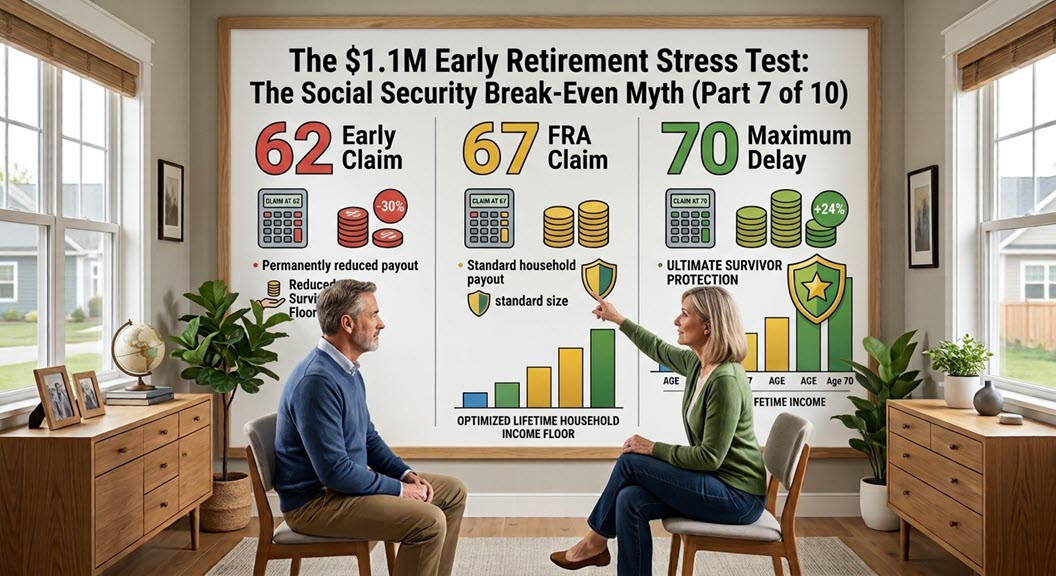
Should you claim Social Security at 62, 67, or 70? We abandon simple break-even calculators to reveal why optimizing your claiming age is the ultimate defense mechanism for surviving spouses.

📌 THE COLLINS FAMILY CASE STUDY ON RETIREMENT R US

Welcome to Week 7 of our ultimate early retirement blueprint! We are charting a complete, math-backed financial roadmap for Henry (55) and Rachel (50) to retire at 58 using their $1.1 million portfolio.
  • In Parts 1 & 2, we built their balance sheet and exposed the flaws of the 4% Rule.
  • In Parts 3 & 4, we stress-tested their portfolio against 10,000 market crashes.
  • In Part 5, we saved them $126,000 in ACA health insurance premiums.
  • In Part 6, we engineered a massive 10-year Roth Conversion schedule.
Today, we tackle the most debated topic in all of retirement planning: When should you claim Social Security?

The Social Security Dilemma

When early retirees approach their 60s, a psychological shift occurs. After decades of paying into the system, the temptation to “get your money back as soon as possible” becomes overwhelming.
Standard financial advice often revolves around a simple “Break-Even Calculator.” These calculators plot out your cumulative lifetime benefits and show you the exact age where delaying your claim finally pays off. While that math is helpful, it is fundamentally incomplete.
For Henry and Rachel Collins, Social Security is not just a monthly paycheck. It is the structural foundation of their entire asymmetric retirement plan. It is their inflation hedge. It is their market-crash insurance. And, most importantly, it is the ultimate financial shield for Rachel if Henry passes away first.
Let’s break down the exact options on the table.

The Collins Family Claiming Options

Henry was the primary breadwinner for most of their marriage, meaning his earnings record dictates the household’s maximum payout.
  • Henry’s Full Retirement Age (FRA): Age 67. His baseline Primary Insurance Amount is $3,750 per month ($45,000 per year).
  • Rachel’s Spousal Benefit: At her own FRA, Rachel is entitled to 50% of Henry’s baseline benefit. That equals $1,875 per month ($22,500 per year).
If they both claim at Full Retirement Age, their guaranteed household income is $67,500 per year. But they don’t have to wait until 67. The government gives them three distinct pathways.

Option 1: Claim at Age 62 (The Early Penalty)

The earliest Henry can claim is age 62. However, because he is claiming five years before his Full Retirement Age, the government imposes a permanent 30% reduction on his payout.
  • Henry’s Reduced Benefit: Drops from $3,750 down to $2,625 per month.
  • Rachel’s Reduced Spousal Benefit: Drops to roughly $1,312 per month.
  • Combined Annual Income: $47,244
By claiming early, they permanently lock in a lower income floor, which means their investment portfolio will have to work much harder to cover their $105,000 living expenses for the rest of their lives.

Option 2: Claim at Age 67 (Full Retirement Age)

If they wait until age 67, there are no penalties. They receive their exact baseline amounts.
  • Combined Annual Income: $67,500
  • This covers a massive 64.2% of their total living budget, dropping their required portfolio withdrawal rate to a highly sustainable 3.41%.

Option 3: Delay Henry’s Benefit to Age 70 (The Maximum Yield)

If Henry does not need the money at 67, he can let his benefit defer. For every year he delays past his FRA, the government awards him an 8% Delayed Retirement Credit. By waiting three years to age 70, his benefit permanently increases by 24%.
  • Henry’s Maximized Benefit: Jumps to $4,650 per month.
  • Rachel’s Spousal Benefit: Remains at the max 50% of Henry’s base, which is $1,875 per month.
  • Combined Annual Income: $78,300

The Break-Even Math

If Henry delays claiming until 70, he misses out on eight years of checks (from 62 to 70). How long does he have to live to make that delay mathematically “worth it”?
If we plot out the cumulative lifetime cash flow of Option 1 (Age 62) versus Option 3 (Age 70), the break-even intersection occurs around Age 78.5.
If Henry passes away before 78.5, claiming early would have yielded more total dollars. If he lives past 78.5, delaying to 70 creates a dramatically higher lifetime payout.
But relying on break-even math is a trap. It assumes Henry is single.

The Real Reason to Delay: Survivor Protection

In marriage, life expectancies are joint, not individual. According to actuarial tables, there is a very high probability that at least one member of a healthy 50-something couple will live well into their 90s.
Because Henry is 5 years older than Rachel, statistics suggest he is likely to predecease her. When one spouse passes away, the surviving spouse’s household income drops—they only get to keep the larger of the two Social Security checks. The smaller check disappears forever.
If Henry claims at 62:
If Henry dies at age 82, Rachel loses her spousal check and steps into Henry’s permanently reduced early benefit of $2,625 per month.
If Henry delays to 70:
If Henry dies at age 82, Rachel steps into his maximized, delayed benefit of $4,650 per month—a payout that is fully adjusted for inflation every single year for the rest of her life.
By delaying his claim to age 70, Henry is effectively buying the cheapest, most powerful longevity insurance available for his wife. He is guaranteeing that Rachel will have an impenetrable financial floor, regardless of what the stock market does in her 80s and 90s.

The “Hidden” Benefit of Delaying: The Tax Valley

There is a final, highly technical reason for Henry to wait until age 70, and it ties directly into the master plan we built in last week’s post.
In Part 6, we engineered a massive 10-year Roth Conversion schedule. We noted that the period between retirement and claiming Social Security creates a pristine “Low-Income Valley”. The sooner Henry and Rachel claim Social Security, the sooner that income starts taking up valuable room in their low-income valley.
Every dollar of Social Security they receive early shrinks the amount of pre-tax 401(k) money they can convert to a Roth IRA at the 12% tax bracket. By delaying Social Security by even a few years, they can meaningfully widen that conversion window.
Delaying to age 70 keeps their visible income effectively at zero, giving them maximum space to move $500,000+ away from the IRS permanently.
Coming Up Next Week in Part 8…
We have built a cash buffer, secured health insurance, converted funds to a Roth, and maximized Social Security. But at age 75, the government comes to collect its debt.
Next week, we are looking at Required Minimum Distributions (RMDs). We will reveal how compulsory distributions stack on top of Social Security to push retirees into elevated tax brackets—and we will prove exactly how the Collins family’s Roth strategy completely defuses this late-in-life tax bomb.

Important Disclosures:  Retirement “R” Us, a registered retirement planning advisor, provides this information for educational purposes only. It is not intended to offer personalized investment advice or suggest that any discussed securities or services are suitable for any specific investor. Readers should not rely solely on the information provided here when making investment decisions.

  • Investing carries risks, including the potential loss of principal. No investment strategy can ensure a profit or protect against loss during market downturns.
  • Past performance is not indicative of future results.
  • The opinions shared are not meant to serve as investment advice or to predict future performance.
  • While we believe the information provided is reliable, we do not guarantee its accuracy or completeness.
  • This content is for educational purposes only and is not intended as personalized advice or a guarantee of achieving specific results. Consult your tax and financial advisors before implementing any discussed strategies.
  • Everyone’s retirement circumstances, especially when it comes to health insurance and health care, are unique.
  • Retirement “R” Us does not provide tax or legal advice. Please consult your tax advisor or attorney for advice tailored to your situation.

Legal Disclaimer:  The information provided on this website is for general informational purposes only and is not intended to be legal advice. While we strive to ensure the accuracy and completeness of the information, we make no guarantees regarding its accuracy, completeness, or timeliness. The content is provided “as is” without any warranties of any kind, either express or implied.

Use of this website does not create an attorney-client relationship between the user and the website owner or any of its contributors. Users should not act upon the information provided without seeking professional legal counsel. Any reliance on the information provided is solely at the user’s own risk.

We are not responsible for any errors or omissions, or for any actions taken based on the information provided on this website. Links to third-party websites are provided for convenience only and do not constitute an endorsement or approval of their content. We are not liable for any damages arising from the use of or reliance on the information provided on this website or any linked third-party websites.

By using this website, you agree to the terms of this legal disclaimer. If you do not agree with these terms, please do not use this website.


Leave a Reply

Your email address will not be published. Required fields are marked *