
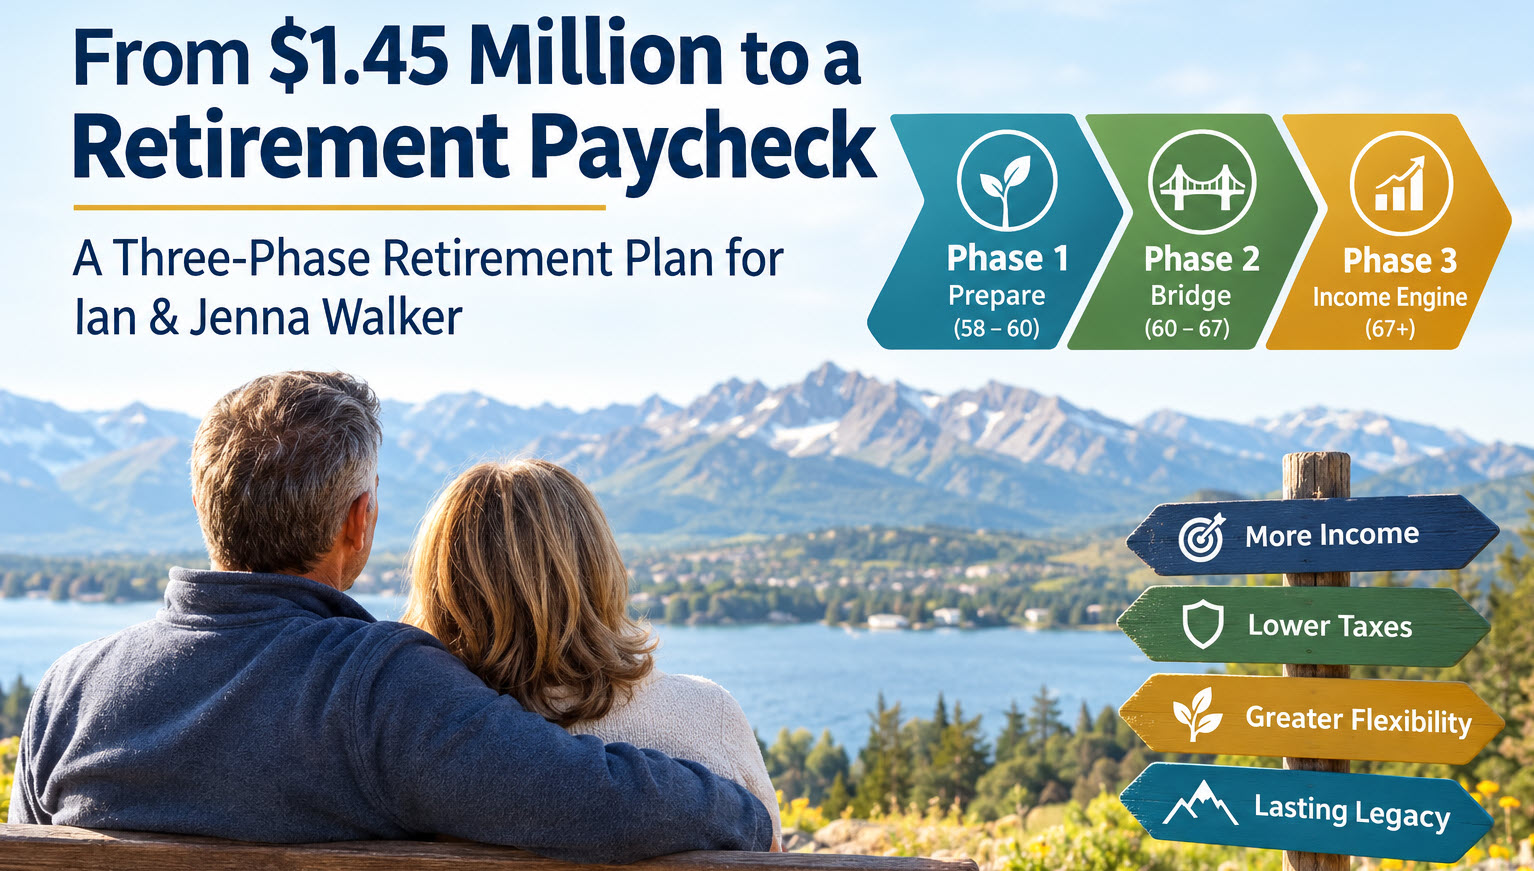
An illustrative Retirement ‘R’ Us case study based on the three-phase retirement framework.
Ian Walker is 58. His wife, Jenna, is 56. They live in Louisville, Colorado, have a 12-year-old child, own their home outright, and have accumulated substantial retirement savings.
Ian plans to retire at 60.
At first glance, their situation looks straightforward: they have approximately $1.45 million in investable financial assets, a $500,000 debt-free home, and a planned retirement spending level of $95,000 per year.
But retirement planning isn’t simply about asking whether $1.45 million is “enough.”
The more important questions are:
- Which account should pay for retirement at different ages?
- How long can the taxable account serve as a bridge?
- Should Jenna continue working after Ian retires?
- When should Ian and Jenna begin Social Security?
- How can they use the lower-income years for Roth conversions?
- How should they manage taxes before and after Medicare?
- How should they protect their portfolio from a major market decline early in retirement?
- How should they preserve the Roth for later-life flexibility?
Those questions are at the heart of the three-phase framework: give every account a job, then build a timeline around those jobs.
The framework emphasizes that retirement isn’t simply about choosing an investment allocation. It is about determining which account funds which years of life and how those withdrawals affect taxes and future income.
Meet Ian & Jenna Walker
Ian is a 58-year-old mechanic earning approximately $105,120 per year. Jenna is 56 and works as a bank teller, earning approximately $50,000 per year.
Together, they earn about:
$155,120 per year
Their retirement spending target is:
$95,000 per year
They have one 12-year-old child, so their retirement plan also needs to account for the remaining years of family expenses and college funding.
Their current financial picture looks like this:
| Account / Asset | Balance |
|---|---|
| Taxable brokerage | $250,000 |
| 401(k) / pre-tax | $1,000,000 |
| Roth IRA | $125,000 |
| Cash / money market | $75,000 |
| Investable financial assets | $1,450,000 |
| Home | $500,000 |
| Mortgage | $0 |
| 529 college savings | $30,000 |
Their home is owned outright, which is an important strength.
Their projected Social Security benefits, using the figures supplied for this case study, are:
- Ian at 67: $3,200/month
- Jenna spousal benefit at 67: $1,600/month
- Combined: $4,800/month
- Annualized: $57,600/year
That future Social Security income could eventually cover a substantial portion of their $95,000 annual spending target.
The First Important Observation: This Is Not a $95,000 Portfolio-Withdrawal Problem
It is easy to look at $95,000 of annual retirement spending and immediately divide it into $1.45 million.
That produces:
$95,000 ÷ $1,450,000 = 6.55%
That number deserves attention.
But it isn’t the complete picture.
Why?
Because Ian isn’t retiring today.
He is planning to retire at 60, and Jenna is only 56 today.
If Jenna continues working after Ian retires, her approximately $50,000 salary could dramatically reduce how much the portfolio needs to provide during the first several years of Ian’s retirement.
For example, suppose retirement spending remains $95,000 and Jenna continues earning $50,000.
The portfolio may initially need to provide approximately:
$95,000 − $50,000 = $45,000
before considering taxes and the precise composition of income.
That is only about:
$45,000 ÷ $1,450,000 = 3.1%
Again, this isn’t a retirement-income calculation or guarantee. Taxes, inflation, investment returns, Jenna’s eventual retirement date, Social Security claiming decisions, and college expenses all matter.
But it demonstrates something extremely important:
Ian’s retirement does not necessarily mean that Ian and Jenna’s household immediately becomes a fully portfolio-funded retirement household.
That distinction should be built into the plan.
The Walker Family’s Retirement Roadmap
The original framework divides retirement into three broad phases:
- Early Retirement Bridge
- Mid-Retirement
- Later Retirement
It then assigns different jobs to taxable, pre-tax and Roth accounts. The framework specifically describes taxable assets as the early-retirement bridge, pre-tax accounts as the future income engine, and Roth assets as long-term growth and flexibility.
For Ian and Jenna, I would modify the timing because Ian isn’t retiring until age 60.
Their roadmap becomes:
| Age | Phase | Primary Funding Source | Main Planning Objective |
|---|---|---|---|
| 58–60 | Pre-Retirement Transition | Employment income + savings | Prepare for Ian’s retirement |
| 60–65 | Early Retirement Bridge | Jenna’s income + Taxable + Cash | Protect portfolio and manage taxes |
| 65–70 | Mid-Retirement | Pre-tax + Social Security transition | Begin controlled IRA withdrawals/conversions |
| 70+ | Later Retirement | RMDs + Social Security + Roth | Manage taxes, large expenses and legacy |
This is where the Walker family’s situation becomes particularly interesting.
Phase 1: Age 58–60 — The Pre-Retirement Transition
Ian still has two years of employment before his planned retirement.
This is not the time to simply wait for age 60.
These two years are an opportunity to build the retirement infrastructure.
The Walker family’s current financial assets total approximately $1.45 million.
But the accounts have very different characteristics:
- $250,000 taxable
- $1 million pre-tax
- $125,000 Roth
- $75,000 cash
The first job is to decide what each account is supposed to accomplish.
The framework makes this point clearly: before determining the precise investments, each account should have a job within the retirement timeline.
Taxable brokerage: the bridge
The $250,000 taxable account is extremely valuable because it isn’t subject to the same age restrictions as retirement accounts.
It can potentially provide income between Ian’s retirement date and the time when other income sources become available.
Cash: the shock absorber
The $75,000 cash/money-market balance is equally important.
It represents roughly:
$75,000 ÷ $95,000 = 0.79 years
of current target spending.
Combined with the taxable account:
$250,000 + $75,000 = $325,000
That represents approximately:
$325,000 ÷ $95,000 = 3.4 years
of spending at today’s spending level, before considering investment returns, taxes, inflation or Jenna’s earnings.
That doesn’t mean they should literally spend $95,000 a year from these accounts.
It demonstrates the size of their potential bridge.
The Child Changes the Early-Retirement Equation
There is another important issue in this case study that shouldn’t be overlooked.
Ian and Jenna have a 12-year-old child.
When Ian retires at 60, their child will be approximately 14.
At age 65, their child will be approximately 19.
That means the early-retirement years overlap with potentially significant college expenses.
They already have:
$30,000 in a 529 plan.
That money should be considered separately from their retirement portfolio.
One mistake would be to mentally count the $30,000 529 balance as retirement assets.
It isn’t.
The 529 has a different job:
Fund education.
Likewise, the taxable account should have a retirement job.
Keeping those purposes separate makes the plan easier to monitor.
Phase 2: Age 60–65 — Ian Retires, Jenna May Still Work
This is probably the most important phase of the Walker retirement plan.
Ian reaches 60 and retires.
Jenna is approximately 58.
The question isn’t necessarily:
“How do we replace $155,120 of employment income?”
Their retirement spending target is $95,000.
Instead, the question becomes:
“How much of the $95,000 does the portfolio actually need to provide while Jenna continues working?”
If Jenna continues earning approximately $50,000, the portfolio may initially have a much smaller role.
This creates an opportunity.
Rather than aggressively withdrawing from the $1 million pre-tax account, the family could potentially use Jenna’s earnings, taxable assets and cash strategically while managing the tax consequences.
The framework describes this period as an opportunity to use taxable assets while keeping retirement accounts from being unnecessarily depleted early.
Why the Taxable Account Is So Important
The $250,000 taxable brokerage account is not necessarily the “least important” account simply because it has the smallest balance.
In early retirement, it may be the account with the greatest strategic importance.
Why?
Because Ian and Jenna have more control over when taxable income is recognized.
They can potentially:
- Sell investments with long-term capital gains.
- Use available cash for spending.
- Coordinate withdrawals with Jenna’s wages.
- Avoid unnecessary early retirement-account withdrawals.
- Create opportunities for Roth conversions when taxable income is lower.
The framework describes the taxable account as both a spending bridge and a tax-planning tool because withdrawals can be controlled more flexibly than withdrawals from traditional retirement accounts.
But There Is a Problem: $250,000 Isn’t a Five-Year Bridge
Suppose, hypothetically, that the entire $95,000 annual spending requirement came from the taxable account.
$250,000 ÷ $95,000 is only about:
2.6 years.
Even adding the $75,000 cash reserve produces approximately:
3.4 years.
That’s important.
The Walker family should not think:
“We have $250,000 taxable, so we’re covered until 65.”
They aren’t—at least not if the portfolio had to fund the entire $95,000 spending requirement.
But that isn’t necessarily their situation.
Jenna’s continued employment could dramatically extend the life of those assets.
That is why her retirement date becomes one of the most important variables in the plan.
The $1 Million Pre-Tax Account Is the Future Income Engine
The Walker family has approximately:
$1,000,000 in pre-tax retirement accounts.
This is their largest financial asset.
But it also represents future taxable income.
Traditional 401(k) and IRA withdrawals are generally taxable as ordinary income.
The framework emphasizes that pre-tax accounts should not simply be viewed as money to leave untouched forever. They need to be deliberately shaped into a future income source while managing the tax consequences.
That creates an interesting opportunity for Ian and Jenna.
The Roth Conversion Window
Imagine Ian retires at 60.
His salary disappears.
Jenna continues working, perhaps at approximately $50,000.
Their household taxable income could potentially fall substantially compared with their current working years.
That may create years in which Roth conversions become worth evaluating.
For example, instead of waiting until later retirement and allowing the entire $1 million pre-tax account to remain untouched, they could evaluate annual partial conversions.
The objective isn’t:
“Convert the entire $1 million to Roth.”
The objective is:
Use available lower tax brackets strategically without creating an unnecessarily large tax bill today.
The source framework makes exactly this distinction: Roth conversions are about smoothing future taxable income rather than automatically converting everything before RMDs.
For the Walkers, this could potentially be one of the most valuable planning opportunities between Ian’s retirement and the beginning of Social Security and required distributions.
But every conversion needs to be modeled against:
- Current federal taxes
- Colorado taxes
- Jenna’s wages
- Capital gains
- Social Security timing
- Future RMDs
- Medicare premiums
- Other deductions and credits
The right conversion amount could change every year.
The Roth IRA: Don’t Treat It Like Just Another Investment Account
The Walker family has:
$125,000 Roth IRA
Compared with their $1 million pre-tax balance, this may look relatively small.
But its value isn’t simply its current balance.
The Roth provides an account with a different tax characteristic.
The framework recommends treating Roth assets as a long-term growth and flexibility account rather than automatically spending them early.
That makes sense for Ian and Jenna’s timeline.
If the Roth remains invested for another 15, 20 or 25 years, it could become an increasingly valuable source of tax-free flexibility later in life.
What Could the Roth Be Used For Later?
Imagine Ian and Jenna are in their 70s.
They have:
- Social Security
- Required minimum distributions
- Other taxable income
Then they need $40,000 for a major home renovation.
Or perhaps they want to purchase a vehicle.
Or help their child financially.
A withdrawal from a traditional account could increase taxable income.
A qualified Roth withdrawal can potentially provide the money without adding ordinary income.
That is why the Roth isn’t simply another bucket of retirement money.
It is an income-flexibility tool.
The framework specifically identifies Roth assets as particularly useful later in retirement when other sources of taxable income become less flexible.
Phase 3: Age 65–70 — Social Security Enters the Picture
The next major transition occurs around age 67.
The Walker family’s supplied Social Security estimates are:
| Social Security | Monthly | Annual |
|---|---|---|
| Ian | $3,200 | $38,400 |
| Jenna spousal | $1,600 | $19,200 |
| Combined | $4,800 | $57,600 |
Against $95,000 of annual spending, that leaves:
$95,000 − $57,600 = $37,400
of spending that would need to come from other sources, before accounting for taxes and assuming the supplied benefits are realized as stated.
This is a major change from the early retirement years.
Social Security eventually becomes a significant portion of their retirement-income engine.
The portfolio no longer has to carry the entire burden.
This Is Why the Retirement Timeline Matters
Consider the difference between these two situations.
Age 60
Ian has retired.
Jenna may still be earning $50,000.
Social Security hasn’t started.
The portfolio may need to provide only part of the household’s spending.
Age 67
Ian’s projected Social Security is $38,400.
Jenna’s supplied spousal benefit is $19,200.
Together, that’s $57,600.
The portfolio’s required role could become much smaller.
This is exactly why retirement planning shouldn’t be based on one withdrawal percentage applied from age 60 through age 90.
The framework describes retirement as a sequence of different “seasons,” with different sources of income and different risks in each period.
Phase 4: Age 70+ — RMDs Become Part of the Plan
Eventually, required minimum distributions enter the picture for the applicable pre-tax accounts.
This changes the retirement strategy again.
The $1 million pre-tax account is no longer simply a reserve for the future.
It becomes a source of required taxable income.
That is another reason the years between Ian’s retirement and later retirement can be valuable.
If the Walkers can strategically reduce their pre-tax balance through appropriate withdrawals or Roth conversions during lower-income years, they may have more flexibility later.
But again, the objective isn’t necessarily to eliminate the traditional retirement account.
A traditional account can still be an extremely useful source of retirement income.
The goal is to avoid creating a future situation where:
Social Security + RMDs + other income = unnecessarily high taxable income.
The Three Account Jobs
The Walker family’s plan becomes much easier to understand if we stop looking at their accounts as one giant $1.45 million portfolio.
Instead, give each bucket a job.
| Account | Current Balance | Primary Job |
|---|---|---|
| Taxable brokerage | $250,000 | Early-retirement bridge + tax flexibility |
| Cash/MMF | $75,000 | Near-term spending + emergency reserve |
| 401(k)/pre-tax | $1,000,000 | Long-term retirement income + Roth conversion opportunity |
| Roth IRA | $125,000 | Long-term tax-free growth + later-life flexibility |
| 529 | $30,000 | College funding |
| Home | $500,000 | Housing + potential future flexibility |
This is much more useful than saying:
“The Walkers have $1.45 million invested.”
The balances tell us how much they have.
The account jobs tell us how the money is supposed to work.
What About Investment Allocation?
This is where many retirement plans start in the wrong place.
The first question shouldn’t be:
“Should they be 60/40 or 70/30?”
The first question should be:
“How much money must be stable because they need it soon?”
The framework emphasizes that the early retirement years carry significant sequence-of-returns risk and suggests thinking about the money needed over the next several years before determining the overall stock/bond mix.
For Ian and Jenna, this matters because Ian is approaching retirement.
A significant market decline immediately after Ian retires could be more damaging than the same decline 15 years later.
Why Sequence-of-Returns Risk Matters
Suppose Ian retires at 60.
Six months later, the stock market falls substantially.
If the Walkers are forced to sell a large amount of stocks to pay their $95,000 annual expenses, they could permanently reduce the number of shares available to participate in the eventual recovery.
But if they have sufficient cash, bonds and taxable resources to cover near-term expenses, they have more flexibility.
That’s the purpose of having a spending reserve.
It isn’t necessarily about predicting the next recession.
It is about reducing the need to sell volatile assets at an unfavorable time.
Asset Location May Matter More Than a Single Portfolio Allocation
The Walkers don’t necessarily need every account to have the exact same investment mix.
The framework specifically argues against automatically making every account identical and instead considers what each account needs to accomplish.
Conceptually, that could mean:
Taxable
Emphasize tax-efficient investments and maintain enough liquidity for the early-retirement spending role.
Pre-tax
Use a meaningful allocation toward assets appropriate for future income needs and portfolio stability.
Roth
Because the Walkers expect to leave the Roth invested for longer, it may have a greater capacity for long-term growth assets.
The exact investments and percentages would require a separate risk assessment.
The $500,000 Home Is an Important Part of the Plan
The Walkers own their home outright.
That’s a major structural advantage.
They have:
$500,000 of home value
with:
$0 mortgage.
That means their $95,000 annual spending target does not include a mortgage payment.
The home also provides future options.
It could remain their residence for life.
They could downsize.
They could eventually sell it.
They could potentially use some of the equity later in retirement.
But there is an important planning principle here:
Don’t count home equity as retirement income unless you have a specific plan for using it.
For now, the safest way to look at the $500,000 is as a separate asset.
The retirement income plan should work without depending on a future home sale unless the Walkers deliberately decide otherwise.
The College Funding Question
The $30,000 529 account is another important part of the plan.
Their child is 12.
That means college may be only several years away.
The Walkers therefore have two major financial transitions happening almost simultaneously:
Ian retires at 60
and
their child enters college around the same general period.
That deserves special attention.
A retirement plan that works perfectly on paper can become much more complicated if the family suddenly needs large amounts of money for college while Ian is no longer earning $105,120.
This is another reason the taxable account and cash reserves should not be viewed as completely available retirement spending money.
Some of those resources may have competing jobs.
A Simple Income Waterfall
The Walker retirement-income strategy can be visualized as a waterfall.
Ages 60–65
Jenna’s employment income
↓
Cash / taxable brokerage
↓
Potential controlled pre-tax withdrawals
↓
Roth conversion opportunities
Ages 65–67+
Jenna’s employment income, if still working
↓
Taxable assets
↓
Pre-tax retirement accounts
↓
Social Security begins
↓
Roth preserved for flexibility
Age 70+
Social Security
RMDs / pre-tax withdrawals
↓
Normal retirement spending
↓
Roth for major expenses, tax management and legacy
That is the fundamental transformation.
Instead of asking:
“How do we withdraw $95,000 every year?”
we ask:
“Which source should provide each dollar at each stage of retirement?”
The Most Important Planning Opportunity: The Years Between 60 and 67
For Ian and Jenna, the period between Ian’s retirement at 60 and Social Security at 67 could be the most important tax-planning window.
Why?
Because Ian’s employment income disappears.
But Social Security hasn’t yet started.
Required distributions haven’t necessarily become the dominant source of income.
Jenna may still be working, but household income could still be significantly lower than it is today.
That could create an opportunity to evaluate:
- Roth conversions
- Capital-gain realization
- Pre-tax withdrawals
- Taxable-account spending
- Social Security timing
- Medicare planning
- College funding
- Portfolio rebalancing
The framework emphasizes building a year-by-year map that tracks spending, which account provides it, taxable income, Social Security, RMDs and Medicare-related income thresholds.
For the Walkers, that annual map is arguably more valuable than simply choosing a portfolio allocation.
A Potential Year-by-Year Framework
Here’s how I would organize the Walker family’s planning model.
| Age | Ian | Jenna | Primary Planning Focus |
|---|---|---|---|
| 58 | Working | Working | Build retirement reserves |
| 59 | Working | Working | Final retirement preparation |
| 60 | Retires | Working | Begin retirement-income transition |
| 61 | Retired | Working | Taxable/cash + Jenna’s income |
| 62 | Retired | Working | Evaluate Roth conversion |
| 63 | Retired | Working | Evaluate taxes and healthcare |
| 64 | Retired | Working/transition | Prepare for Medicare |
| 65 | Retired | ~63 | Medicare/healthcare transition |
| 66 | Retired | ~64 | Continue tax management |
| 67 | Retired | ~65 | Social Security becomes significant |
| 68–69 | Retired | Retired/transition | Portfolio + Social Security |
| 70+ | Retired | Retired | RMD/tax/Roth strategy |
The exact timing of Jenna’s retirement is one of the biggest variables that still needs to be determined.
What Could Go Wrong?
A good retirement plan doesn’t just show the happy scenario.
It identifies where the plan could become stressed.
For Ian and Jenna, I would monitor at least six risks.
1. Ian retires and Jenna stops working earlier than expected
This would increase the portfolio’s required withdrawals.
2. A major market decline occurs around age 60
This increases sequence-of-returns risk.
3. College expenses are larger than expected
This could compete with retirement spending.
4. Healthcare costs are higher than expected
The years before Medicare need particular attention.
5. The $1 million pre-tax account grows substantially
That sounds like a good problem—but a larger pre-tax account can also produce larger future taxable distributions.
6. Spending rises above $95,000
Inflation, travel, home repairs, vehicles, family assistance and healthcare can all change actual spending.
The Plan Should Not Be Built Around One Perfect Return
Another common mistake is assuming that a portfolio will earn some smooth average return every year.
Real markets don’t work that way.
A retirement portfolio might experience:
- +12%
- −18%
- +7%
- +2%
- −10%
and still eventually produce a reasonable long-term average.
But withdrawals don’t happen in averages.
They happen in actual calendar years.
The framework makes this distinction explicitly: markets operate around average returns, while taxes, Medicare and household expenses operate on calendar years.
That’s why the Walkers need a year-by-year retirement-income model.
What Would Make This Plan Stronger?
There are several pieces I would want Retirement ‘R’ Us to examine before telling Ian and Jenna that they are fully retirement-ready.
First: Determine Jenna’s retirement date
This is huge.
There is a major difference between Jenna working until:
- 60
- 62
- 65
- 67
Her continued $50,000 income could substantially reduce early portfolio withdrawals.
Second: Build a detailed Social Security analysis
The supplied $3,200 and $1,600 monthly amounts should be tested at different claiming ages.
Third: Build the Roth-conversion schedule
Instead of asking:
“Should they convert to Roth?”
ask:
“How much should they convert each year?”
Fourth: Separate college money from retirement money
The $30,000 529 should have its own funding plan.
Fifth: Build a healthcare timeline
The plan should specifically address the period between Ian’s retirement and Medicare eligibility and then the transition into Medicare.
Sixth: Run stress tests
The plan should be tested against:
- Poor early market returns
- Higher inflation
- Longer life expectancy
- Higher healthcare costs
- Higher college costs
- Earlier retirement for Jenna
- Higher annual spending
The Walker Family’s Retirement Picture
At the current snapshot, Ian and Jenna have approximately:
$1.45 million of investable assets
plus:
$500,000 of home equity
plus:
$30,000 in their 529.
Their financial picture is therefore much larger than simply saying they have “$1.45 million saved.”
But the more important number isn’t the total.
It’s the structure.
They have:
- A taxable account for flexibility
- $75,000 of cash
- A substantial pre-tax retirement account
- A Roth IRA
- A debt-free home
- A 529
- Two incomes today
- A future Social Security income stream
The challenge is coordinating all of those pieces.
The Retirement ‘R’ Us Three-Phase Strategy
For Ian and Jenna, the strategy can be summarized like this:
Phase 1 — Prepare
Age 58–60
Ian continues working.
Jenna continues working.
The priority is accumulating additional assets, building liquidity, protecting the early-retirement spending reserve and preparing the tax strategy.
Primary objective:
Enter Ian’s retirement with a clear income map rather than simply a large portfolio.
Phase 2 — Bridge
Age 60–67
Ian retires.
Jenna may continue working.
Use employment income, cash and taxable assets strategically.
Consider controlled pre-tax withdrawals and Roth conversions when the tax picture makes sense.
Primary objective:
Get through the early retirement years without unnecessarily damaging the long-term portfolio or creating future tax problems.
Phase 3 — Income Engine
Age 67–70+
Social Security becomes a major income source.
Pre-tax accounts become increasingly important.
RMDs eventually enter the picture.
The Roth becomes increasingly valuable as a source of tax-free flexibility.
Primary objective:
Coordinate Social Security, RMDs, taxable income and Roth assets so the portfolio continues supporting the Walkers throughout later retirement.
The Bigger Lesson
Ian and Jenna don’t need to think of their retirement as one giant $1.45 million portfolio.
They need to think of it as a series of financial jobs.
Their taxable account has one job.
Their cash has another.
Their $1 million pre-tax account has another.
Their Roth has another.
Their 529 has another.
Their home has another.
And those jobs change as Ian and Jenna move from their late 50s into their 60s, 70s and beyond.
That’s the central idea behind a three-phase retirement strategy.
The framework’s original case study makes the same fundamental point: a retirement portfolio should be designed around when money is needed, which account provides it, and how that decision affects taxes and future flexibility—not simply around selecting a single investment allocation.
For Ian and Jenna, the biggest planning opportunity may not be finding a magical investment.
It may be coordinating the seven years between Ian’s retirement at 60 and the beginning of their projected Social Security benefits at 67.
Those years could determine how efficiently their $1 million pre-tax account is converted into a lifetime income source, how much of their taxable account survives, how much flexibility they retain in their Roth, and how smoothly they transition from employment income to retirement income.
Three Next Actions for Ian & Jenna
1. Build a year-by-year retirement income map from age 58 through at least age 90.
Track employment income, spending, taxable withdrawals, 401(k) withdrawals, Roth conversions, Social Security, taxes and RMDs.
2. Determine Jenna’s optimal retirement date.
Her $50,000 income could materially change the amount the portfolio needs to provide during Ian’s first several years of retirement.
3. Build a Roth-conversion and Social Security strategy together.
Don’t analyze these decisions independently. The timing of one can materially affect the tax picture of the other.
A Final Thought for Future Retirees
The Walker family’s story illustrates why having a certain amount of money saved doesn’t automatically tell you whether you’re ready to retire.
Two households can have exactly the same $1.5 million portfolio and have very different retirement outcomes depending on:
- when they retire,
- when their spouse retires,
- which account they spend first,
- when Social Security begins,
- how much taxable income they create,
- how much they convert to Roth,
- how much they spend,
- and how their portfolio behaves during the first several years.
The goal isn’t simply to have $1.45 million.
The goal is to turn that $1.45 million into a structured, tax-aware retirement income system that evolves as Ian and Jenna move through each phase of retirement.
That is the difference between having a collection of accounts and having a retirement plan.
Important Disclosures: Retirement “R” Us, a registered retirement planning advisor, provides this information for educational purposes only. It is not intended to offer personalized investment advice or suggest that any discussed securities or services are suitable for any specific investor. Readers should not rely solely on the information provided here when making investment decisions.
- Investing carries risks, including the potential loss of principal. No investment strategy can ensure a profit or protect against loss during market downturns.
- Past performance is not indicative of future results.
- The opinions shared are not meant to serve as investment advice or to predict future performance.
- While we believe the information provided is reliable, we do not guarantee its accuracy or completeness.
- This content is for educational purposes only and is not intended as personalized advice or a guarantee of achieving specific results. Consult your tax and financial advisors before implementing any discussed strategies.
- Everyone’s retirement circumstances, especially when it comes to health insurance and health care, are unique.
- Retirement “R” Us does not provide tax or legal advice. Please consult your tax advisor or attorney for advice tailored to your situation.
Legal Disclaimer: The information provided on this website is for general informational purposes only and is not intended to be legal advice. While we strive to ensure the accuracy and completeness of the information, we make no guarantees regarding its accuracy, completeness, or timeliness. The content is provided “as is” without any warranties of any kind, either express or implied.
Use of this website does not create an attorney-client relationship between the user and the website owner or any of its contributors. Users should not act upon the information provided without seeking professional legal counsel. Any reliance on the information provided is solely at the user’s own risk.
We are not responsible for any errors or omissions, or for any actions taken based on the information provided on this website. Links to third-party websites are provided for convenience only and do not constitute an endorsement or approval of their content. We are not liable for any damages arising from the use of or reliance on the information provided on this website or any linked third-party websites.
By using this website, you agree to the terms of this legal disclaimer. If you do not agree with these terms, please do not use this website.
Leave a Reply