
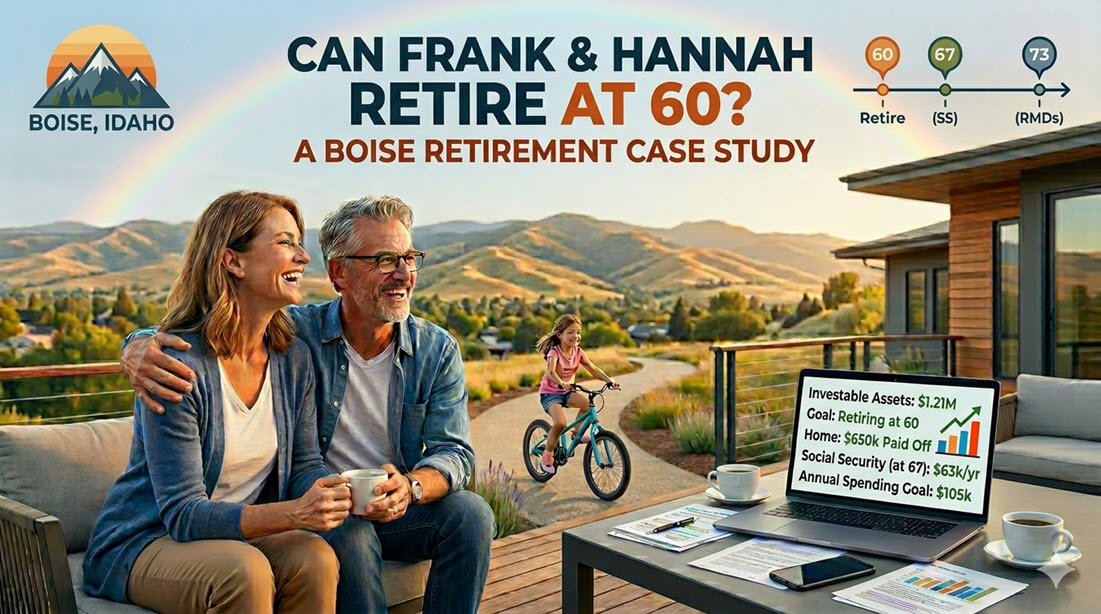
A Retirement Tax & Income Planning Case Study for a Boise Family
By Retirement “R” Us
Retirement planning is about far more than accumulating a large portfolio. The real challenge is converting decades of savings into a sustainable, tax-efficient income stream that lasts throughout retirement.
In this case study, we’ll examine Frank and Hannah Porter, a Boise, Idaho family hoping to retire when Frank reaches age 60. We’ll evaluate their strengths, identify potential risks, and explore the tax planning opportunities that could significantly improve their long-term retirement success.
Meet Frank & Hannah
Family Profile
| Item | Details |
|---|---|
| Ages | 57 and 55 |
| Location | Boise, Idaho |
| Occupation | Computer Security Officer |
| Spouse | Stay-at-Home Mom |
| Child | Age 8 |
| Target Retirement | Both retire when Frank turns 60 |
| Current Income | $167,000 |
| Annual Retirement Spending Goal | $105,000 |
Current Assets
| Asset | Value |
|---|---|
| 401(k) | $789,000 |
| Taxable Brokerage | $259,000 |
| Roth IRA | $105,000 |
| Cash/MMF | $65,000 |
| 529 Plan | $24,000 |
| Home Value | $650,000 |
| Mortgage | $0 |
Total Investable Assets
$1,218,000
Estimated Net Worth
$1.87 Million
The Retirement Question
The Porters want to know:
“Can we retire when Frank reaches age 60 and maintain our lifestyle without running out of money?”
The answer appears encouraging, but several factors will determine whether retirement is merely possible or truly optimized.
The Five Biggest Strengths
Strength #1: No Mortgage
One of the most significant advantages Frank and Hannah possess is owning their home outright.
Many retirees enter retirement with monthly mortgage payments ranging from $1,500 to $3,500. The Porters don’t have this burden.
Why This Matters
Without a mortgage:
- Monthly expenses are lower
- Less income is required from investments
- Market downturns become easier to navigate
- Retirement cash flow becomes more predictable
Example
Suppose another retired couple needs:
- $105,000 annual spending
- $24,000 annual mortgage payment
Their actual retirement need becomes:
$129,000 annually
Frank and Hannah need only:
$105,000 annually
Using the traditional 4% withdrawal rule, that $24,000 annual difference is equivalent to needing roughly:
$600,000 less in retirement savings.
Owning their home free and clear is like having an additional retirement asset working in the background.
Strength #2: Strong Savings Foundation
The Porters have accumulated over $1.2 million in investable assets.
This includes:
- $789,000 in a 401(k)
- $259,000 in taxable investments
- $105,000 in Roth assets
- $65,000 in cash reserves
Why This Matters
The most important retirement variable isn’t investment returns.
It’s how much money you’ve accumulated before retirement.
Frank and Hannah have built a strong foundation that provides flexibility and resilience.
Example
If their portfolio grows at an average annual rate of 6% during the next three years before retirement:
$1,218,000 × 1.06³
The portfolio could grow to approximately:
$1.45 million
without adding another dollar.
That’s over $230,000 of additional growth before retirement begins.
Strength #3: Strong Social Security Benefits
Projected Social Security benefits at age 67:
| Person | Monthly Benefit |
|---|---|
| Frank | $3,500 |
| Hannah | $1,750 |
| Combined | $5,250 |
Annual household benefit:
$63,000
Why This Matters
Social Security functions much like an inflation-adjusted pension.
Benefits:
- Guaranteed for life
- Adjusted annually for inflation
- Not dependent on stock market performance
- Provides longevity protection
Example
Their retirement spending target is:
$105,000
Social Security covers:
$63,000
That means their portfolio only needs to generate:
$42,000 annually
once benefits begin.
This dramatically reduces retirement pressure.
Strength #4: Significant Taxable Assets
The Porters have approximately:
- $259,000 in taxable investments
- $65,000 in cash
Total liquid assets:
$324,000
Why This Matters
Taxable assets create planning flexibility.
Many retirees have nearly all their money inside IRAs and 401(k)s, forcing them to create taxable income whenever money is needed.
The Porters have options.
Example
Suppose they need $50,000 during their first retirement year.
Instead of withdrawing from their 401(k) and paying ordinary income taxes, they may be able to use taxable assets and manage capital gains more efficiently.
This becomes especially valuable during Roth conversion years.
Strength #5: Long Retirement Planning Horizon
Frank and Hannah could spend 30 to 35 years in retirement.
While many people view this as a risk, it also creates opportunities.
Why This Matters
Long retirements allow:
- Continued portfolio growth
- Tax planning opportunities
- Roth conversion strategies
- Estate planning flexibility
Example
A portfolio that continues earning reasonable returns while withdrawals remain moderate may still grow substantially over time.
This creates a greater likelihood of:
- Meeting healthcare needs
- Funding long-term care
- Leaving a legacy for children
The Five Biggest Risks
No retirement plan is perfect.
Let’s examine the risks that deserve attention.
Risk #1: A Young Child at Retirement
Most retirees no longer have dependent children.
The Porters will.
Their child is currently age 8 and will only be about 11 years old when retirement begins.
Why This Matters
Major expenses still lie ahead:
- School activities
- Sports
- Transportation
- College
- Healthcare
Example
If college costs average:
$35,000 per year
for four years, total costs could exceed:
$140,000
Current 529 balance:
$24,000
Additional planning and contributions will likely be needed.
Risk #2: Heavy Reliance on Pre-Tax Retirement Accounts
Approximately:
65% of investable assets
are inside a traditional 401(k).
Why This Matters
Every future withdrawal creates taxable income.
Potential consequences include:
- Higher federal taxes
- Idaho state taxes
- Increased Social Security taxation
- Medicare premium surcharges
Example
A $50,000 withdrawal from a traditional IRA is fully taxable.
A $50,000 withdrawal from a Roth IRA is generally tax-free.
The tax difference over a 30-year retirement can be substantial.
Risk #3: Future Required Minimum Distributions (RMDs)
Beginning at age 73, the IRS requires withdrawals from traditional retirement accounts.
These withdrawals occur whether the money is needed or not.
Why This Matters
Large accounts create large RMDs.
Large RMDs often trigger:
- Higher tax brackets
- More Social Security taxation
- Increased Medicare premiums
Example
If the Porters’ pre-tax accounts grow to $1.8 million by age 73:
Their first RMD could exceed:
$65,000 annually
before considering Social Security or investment income.
This can create significant tax pressure.
Risk #4: Healthcare Before Medicare
Retiring at age 60 creates a five-year gap before Medicare eligibility at age 65.
Why This Matters
Healthcare is often one of the largest retirement expenses.
Many retirees underestimate these costs.
Example
Private health insurance for a couple in their early 60s may cost:
$12,000 to $20,000+ annually
depending on:
- Income
- Coverage level
- Subsidy eligibility
Healthcare planning should be part of every retirement income strategy.
Risk #5: Sequence of Returns Risk
This is one of the least understood retirement risks.
What Is It?
Poor market returns early in retirement can permanently damage a portfolio.
Example
Suppose retirement begins with:
$1.2 million
A market decline of 20% reduces assets to:
$960,000
Then a $105,000 withdrawal is taken.
Remaining balance:
$855,000
Even if markets recover later, less money remains invested to participate in the recovery.
This is why the first decade of retirement is often the most important.
The Biggest Opportunity: The Roth Conversion Window
The Porters may have a unique tax planning opportunity.
Retirement Timeline
| Age | Event |
|---|---|
| 60 | Retirement |
| 65 | Medicare Begins |
| 67 | Social Security Begins |
| 73 | RMDs Begin |
This creates approximately seven years between retirement and Social Security.
These years may be the lowest-tax years of their lives.
Why Roth Conversions Matter
Current pre-tax assets:
$789,000
Potential annual Roth conversions:
$30,000 to $60,000
Over seven years:
Potential conversions:
$210,000 to $420,000
Benefits include:
- Lower future RMDs
- Reduced Social Security taxation
- Lower Medicare premium risk
- Tax-free future growth
- Improved inheritance outcomes
For many retirees, this period represents the single greatest tax-saving opportunity of retirement.
Social Security Strategy
Current projections:
- Frank: $3,500/month at 67
- Hannah: $1,750/month at 67
Combined:
$63,000 annually
Should Frank Delay Until 70?
Possibly.
Delaying benefits from age 67 to age 70 increases benefits by approximately:
24%
Frank’s benefit could potentially rise to approximately:
$4,340 per month
Benefits of delaying:
- Larger guaranteed income stream
- Greater survivor protection
- Less dependence on portfolio withdrawals
This should be modeled before filing.
Retirement Readiness Scorecard
| Category | Assessment |
|---|---|
| Savings Level | Strong |
| Home Ownership | Excellent |
| Social Security | Strong |
| Tax Diversification | Moderate |
| Roth Opportunity | Excellent |
| College Planning | Needs Attention |
| Healthcare Planning | Needs Review |
| Overall Retirement Outlook | Strong |
Final Thoughts
Frank and Hannah appear well-positioned to retire when Frank reaches age 60.
Their mortgage-free home, healthy savings balance, and future Social Security benefits provide a solid retirement foundation. However, their greatest opportunity lies in the seven-year period between retirement and Social Security.
By strategically managing withdrawals and implementing annual Roth conversions, they may be able to reduce lifetime taxes, lower future RMDs, and create a more efficient retirement income plan.
Retirement success isn’t just about how much you’ve saved.
It’s about how efficiently you use what you’ve saved.
For the Porters, thoughtful tax planning may be the difference between a good retirement and a great one.
Key Takeaway
The Porters’ retirement plan appears strong today, but the years between ages 60 and 67 may be the most valuable tax-planning years of their entire lives. Properly executed Roth conversions during this window could save tens of thousands of dollars in taxes while improving retirement flexibility for decades to come.
Important Disclosures: Retirement “R” Us, a registered retirement planning advisor, provides this information for educational purposes only. It is not intended to offer personalized investment advice or suggest that any discussed securities or services are suitable for any specific investor. Readers should not rely solely on the information provided here when making investment decisions.
- Investing carries risks, including the potential loss of principal. No investment strategy can ensure a profit or protect against loss during market downturns.
- Past performance is not indicative of future results.
- The opinions shared are not meant to serve as investment advice or to predict future performance.
- While we believe the information provided is reliable, we do not guarantee its accuracy or completeness.
- This content is for educational purposes only and is not intended as personalized advice or a guarantee of achieving specific results. Consult your tax and financial advisors before implementing any discussed strategies.
- Everyone’s retirement circumstances, especially when it comes to health insurance and health care, are unique.
- Retirement “R” Us does not provide tax or legal advice. Please consult your tax advisor or attorney for advice tailored to your situation.
Legal Disclaimer: The information provided on this website is for general informational purposes only and is not intended to be legal advice. While we strive to ensure the accuracy and completeness of the information, we make no guarantees regarding its accuracy, completeness, or timeliness. The content is provided “as is” without any warranties of any kind, either express or implied.
Use of this website does not create an attorney-client relationship between the user and the website owner or any of its contributors. Users should not act upon the information provided without seeking professional legal counsel. Any reliance on the information provided is solely at the user’s own risk.
We are not responsible for any errors or omissions, or for any actions taken based on the information provided on this website. Links to third-party websites are provided for convenience only and do not constitute an endorsement or approval of their content. We are not liable for any damages arising from the use of or reliance on the information provided on this website or any linked third-party websites.
By using this website, you agree to the terms of this legal disclaimer. If you do not agree with these terms, please do not use this website.
Leave a Reply