
📌 THE COLLINS FAMILY CASE STUDY ON RETIREMENT R US
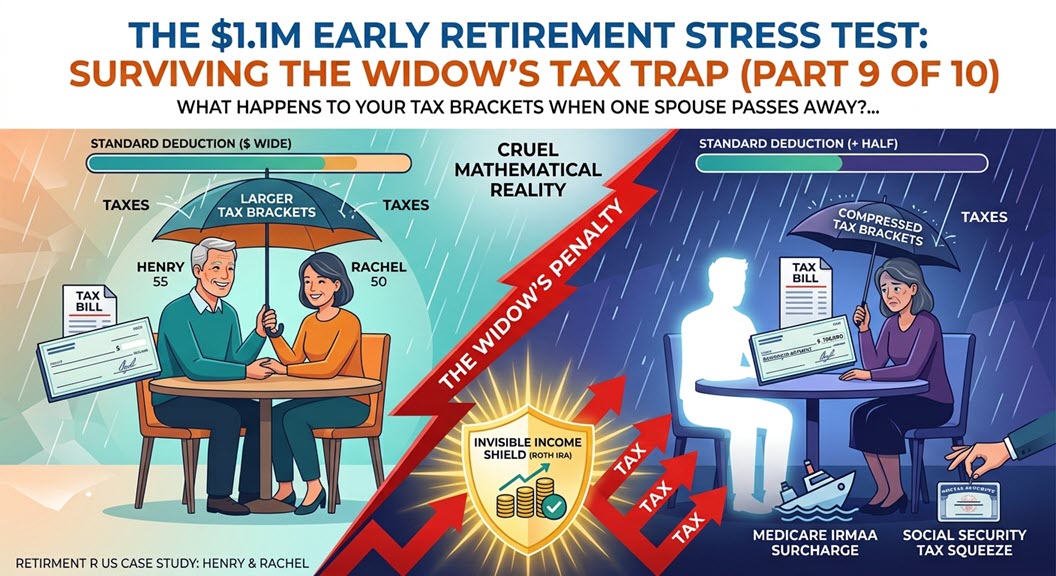
Welcome back to week 9 of our ultimate early retirement blueprint! We are mapping a mathematically bulletproof plan for Henry (55) and Rachel (50) to retire at 58 with a $1.1 million portfolio.
The Hidden Retirement Threat
The Cruel Arithmetic of Filing Single
1. The Standard Deduction Collapses
2. The Tax Brackets Compress
The Collateral Damage: Medicare and Social Security
-
The Medicare IRMAA Surcharge: In Part 8, we discussed the Medicare IRMAA cliff. For a married couple, the government won’t impose Medicare premium surcharges until their combined income crosses $218,000. But for a single widow? That cliff is slashed exactly in half to $109,000. A surviving spouse could suddenly find herself paying thousands of dollars more per year for the exact same Medicare coverage, simply because she crossed a threshold that was never a threat when her husband was alive.
-
The Social Security Squeeze: The threshold for when the IRS taxes 85% of your Social Security benefits is $44,000 for married couples. For a single filer, it drops to $34,000. A widow is instantly forced to pay taxes on a much larger percentage of her sole remaining Social Security check.
The Collins Family Defense Strategy
Second, The Invisible Money Shield:
Coming Up Next Week in the Grand Finale (Part 10)…We have built the ultimate early retirement plan. We have defended against market crashes, health insurance costs, RMDs, and the Widow’s Trap.Next week, we bring it all together. We will reveal the complete, year-by-year chronological checklist of exactly what Henry and Rachel must do from age 58 to age 95 to execute this plan flawlessly. You won’t want to miss the ultimate case study cheat sheet.
Important Disclosures: Retirement “R” Us, a registered retirement planning advisor, provides this information for educational purposes only. It is not intended to offer personalized investment advice or suggest that any discussed securities or services are suitable for any specific investor. Readers should not rely solely on the information provided here when making investment decisions.
- Investing carries risks, including the potential loss of principal. No investment strategy can ensure a profit or protect against loss during market downturns.
- Past performance is not indicative of future results.
- The opinions shared are not meant to serve as investment advice or to predict future performance.
- While we believe the information provided is reliable, we do not guarantee its accuracy or completeness.
- This content is for educational purposes only and is not intended as personalized advice or a guarantee of achieving specific results. Consult your tax and financial advisors before implementing any discussed strategies.
- Everyone’s retirement circumstances, especially when it comes to health insurance and health care, are unique.
- Retirement “R” Us does not provide tax or legal advice. Please consult your tax advisor or attorney for advice tailored to your situation.
Legal Disclaimer: The information provided on this website is for general informational purposes only and is not intended to be legal advice. While we strive to ensure the accuracy and completeness of the information, we make no guarantees regarding its accuracy, completeness, or timeliness. The content is provided “as is” without any warranties of any kind, either express or implied.
Use of this website does not create an attorney-client relationship between the user and the website owner or any of its contributors. Users should not act upon the information provided without seeking professional legal counsel. Any reliance on the information provided is solely at the user’s own risk.
We are not responsible for any errors or omissions, or for any actions taken based on the information provided on this website. Links to third-party websites are provided for convenience only and do not constitute an endorsement or approval of their content. We are not liable for any damages arising from the use of or reliance on the information provided on this website or any linked third-party websites.
By using this website, you agree to the terms of this legal disclaimer. If you do not agree with these terms, please do not use this website.
Leave a Reply